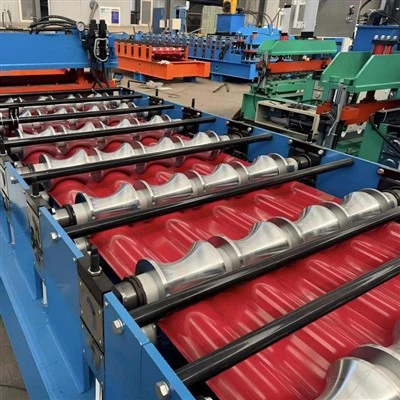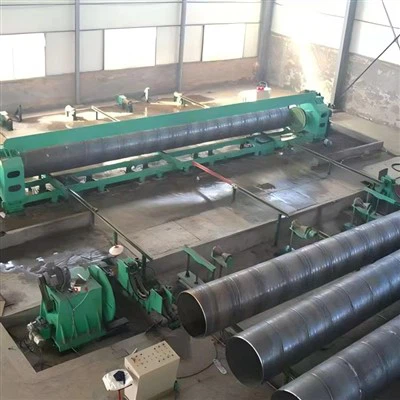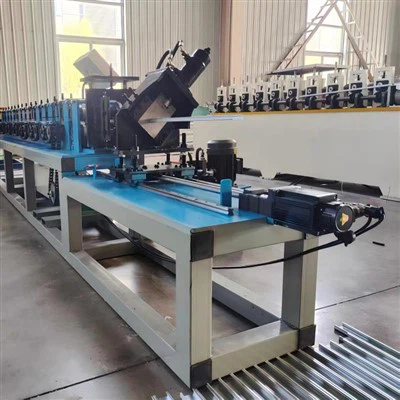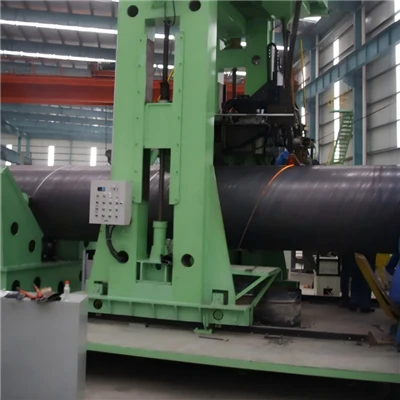
In the next six months (from July to December 2026), global shipping will still be facing political tensions, port congestion, difficulties in vessel capacity allocation, and fluctuating costs. For Chinese steel exporters, especially our company Yashanway, the routes through Sri Lanka, Bangladesh, the Red Sea, the Middle East and West Africa are particularly important for our company. These routes collectively account for over 70% of our company's total exports of steel pipes, pipe-making equipment, and accessories for steel pipe production lines. The following is our analysis of the prospects of each route and its specific impact on our company's foreign trade exports, for your reference.
1. Sri Lanka and Bangladesh routes
The Colombo Port in Sri Lanka, as well as the Chittagong Port in Bangladesh and the Mongla Port in Myanmar, are important transshipment ports for trade in South Asia. In the second half of 2026, with the adjustment of regional transportation routes and the increasing pressure on infrastructure, the roles of these ports will undergo significant changes.
Colombo Port is emerging as the main beneficiary of disrupted transportation in the Red Sea and Persian Gulf. Since the beginning of 2026, congestion and security risks at ports in the Middle East have prompted an additional 20% of transshipment cargo to be redirected to Colombo, and by May 2026, its annual revenue had increased by 20%. Shipping companies such as Maersk and MSC now transfer goods from Asia to the Middle East and from Asia to Africa through Colombo to avoid delays in the Red Sea. For Chinese exporters, this means shorter transportation times to South Asia and East Africa, but higher costs as well. Since the first quarter of 2026, the port handling fees in Colombo have risen by 12%, and the expected peak congestion in the season will increase vessel turnaround time by 3 to 5 days in August. It is expected that the proportion of empty voyages on the China-Colombo route will increase to 6% to 8% in the fourth quarter, as shipping companies prioritize higher-profit routes in the Red Sea and West Africa, resulting in increasingly tight available space.
The ports in Bangladesh face different challenges: long-term congestion, limited capacity of deep-water berths, and rising import demand. Chittagong, which handles 90% of Bangladesh's container trade, has an average port arrival delay of 7 to 10 days by mid-2026, with a port utilization rate exceeding 95%. The recently opened Patenga Container Terminal has slightly alleviated the pressure, but monsoon rains (July to September) will exacerbate the congestion problem and slow down vessel operations. For Chinese exporters shipping to Bangladesh, this means a 30% to 40% extension of the delivery cycle and the need to pay detention fees or port detention charges (up to $150 per container per day). Since June 2026, shipping companies have imposed a "congestion surcharge" of $250 to $300 per TEU, and this may be further increased in the fourth quarter. Additionally, Bangladesh is expected to impose tariffs on Chinese imported steel goods (hot rolled steel, galvanized strip, PPGI, etc.) starting from July 1st, which also leads to increased costs for exporters and importers.
For these 2 markets, customers must prioritize early booking (10 to 14 days in advance) and avoid the peak season's monsoon period and holiday windows (Bangladesh from August to September, Sri Lanka from November to December). Transshipment through alternative hubs such as Singapore or Port of Bussan may reduce congestion risks, but it will increase transportation time by 5 to 7 days per container and cost $200 to $300.
2. Red Sea Route
The Red Sea Route connects Asia and Europe via the Suez Canal and remains the most volatile shipping channel in the second half of 2026. After a partial ceasefire at the end of 2025, the Suez route was partially restored, but in June 2026, the Houthi militants launched another attack and declared a complete ban on ships related to Israel, the United States, or the United Kingdom from passing through. This ban created a "double-layer" situation in the Red Sea: non-target vessels could cautiously resume navigation, while high-risk goods still needed to take a detour around the Cape of Good Hope.
As of mid-2026, only 40% of the capacity was transported through the Suez Canal before the crisis, a significant decrease from 60% in the first quarter of 2026. Major shipping companies such as Maersk and CMA CGM have restored 30% to 40% of the Asia-Europe routes, but they have implemented strict security measures: armed guards, night passage, and prohibiting ships owned by Israel or carrying Israeli goods from entering. For exporters to China, this means they can selectively use the Red Sea Route - non-sensitive goods (such as textiles, furniture, machinery) are prioritized, while high-tech products or those destined for the United States must take a detour around the Cape of Good Hope.
The transportation costs of the Red Sea Route remain high. Although the war risk surcharge has decreased from its peak in 2024, it still increases by $800 to $1,200 per TEU, and the Suez Canal passage fee and security surcharge make the total cost related to the Red Sea account for 25% to 30% of the base freight rate. In contrast, bypassing the Cape of Good Hope avoids war risk costs, but it extends the transportation time by 10 to 14 days and increases fuel costs by 30%. In the peak season of the fourth quarter of 2026, due to demand exceeding the limited safe transportation capacity, shipping companies are likely to increase the Red Sea FAK rate by 15% to 20% (that is, to $2,100 to $2,400 per TEU).
For exporters of steel pipe equipment, the greatest risk is sudden service disruptions. A missile attack by Houthi militants could immediately cause the Red Sea shipping route to be shut down, leaving the goods stranded in unknown ports for several weeks, resulting in some unknown and uncontrollable risks and costs.
3. Middle East Route
The Middle East shipping route (covering the Persian Gulf, the Gulf of Oman, and the Arabian Sea) is facing two threats: the unstable situation in the Strait of Hormuz and port congestion. These two problems are expected to further intensify by the end of 2026. The Strait of Hormuz is a necessary passage for 30% of global oil transportation and 20% of container trade. Since April 2026, due to the US sanctions on Iran's oil exports, Iran has strengthened its maritime patrols and increased the frequency of vessel inspections. Although a complete closure is still unlikely, shipping companies have reduced the cargo volume on the Persian Gulf route by 7.6% and instead transferred goods through alternative hubs such as Salalah (Oman) and Kufrahan (United Arab Emirates).
The major ports in the Middle East, including Jeddah (Saudi Arabia), Dubai (Jebel Ali), and Abu Dhabi, are experiencing record levels of congestion. As the main Red Sea gateway to Saudi Arabia, the berthing delays at Jeddah Port have lasted for 5 to 8 days, prompting Maersk to permanently re-route non-Saudi cargo to Salara and Khufufan in June 2026. The largest container hub in the region, Jebel Ali, is facing issues of overloaded terminals and labor shortages, with the average container detention time extending from 7 days in 2025 to 12 to 15 days. For Chinese exporters to the Middle East, this means longer transportation times (18 to 22 days, compared to 14 days before the crisis) and higher costs: since the first quarter of 2026, base freight rates have increased by 40% to 50%, and the current price of a 40-foot container has exceeded $7,700. Additionally, additional charges - including "Strait Security Fee" (USD 300 to 500 per TEU) and "Congestion Surcharge" (USD 250 to 400 per TEU) - further reduce the profit margin.
Driven by infrastructure construction, consumer goods demand and energy-related projects, China's export demand to the Middle East remains strong. However, in the fourth quarter, a key issue of tight shipping capacity will arise: shipping companies have reduced the capacity in the Persian Gulf by 10% to 15%, and it is expected that the proportion of empty voyages will rise to 8% to 10% from October to December. Exporters need to book shipping space 3 to 4 weeks in advance and consider booking in batches across multiple shipping companies to avoid flight cancellations. For high-value or time-sensitive goods, air freight (although the price is 3 to 4 times higher) may be the only reliable mode of transportation.
4. West African Route
The West African route (covering Nigeria, Ghana, Côte d'Ivoire, Senegal and Sierra Leone) will remain the most expensive and delayed transportation route for Chinese exporters in the second half of 2026. The ports in this region - including Lagos in Nigeria, Tema in Ghana, Abidjan in Côte d'Ivoire, and Dakar in Senegal - have long faced problems such as outdated infrastructure, continuous congestion, and limited capacity for deep-water berths. Coupled with the rising import demand and insufficient transportation capacity, this has further exacerbated operational pressure.
As the busiest port in West Africa, the port of Lagos (Apapa and Kinshasa Island) experiences berthing delays of up to 12 to 15 days, with some ships even needing to wait for three weeks before they can dock. Tema and Freetown also face similar backlog issues, with port utilization exceeding 90% and the average container detention time reaching 20 to 25 days. Seasonal rainfall (from July to September) will further slow down operations, while bureaucratic inefficiencies and corruption at customs will extend clearance times by 5 to 7 days. For Chinese exporters, this means that the voyage duration has increased from 28 to 35 days before the pandemic to 45 to 60 days, with additional costs being high: detention/layover fees can reach $200 per container per day, and port operation fees are 30% to 40% higher than those in Asian ports. Since the first quarter of 2026, freight rates on the China-West Africa route have soared by 50% to 60%, and the price of 40-foot containers has now reached $6,500 to $7,500 per standard container. Shipping companies such as MSC, Maersk, and CMA CGM - which control 70% of the capacity in West Africa - have implemented several additional charges: "Port congestion surcharge" (300 to 500 US dollars per TEU), "Fuel adjustment factor (BAF)" (up 12% to 15% compared to the previous month), and "Security surcharge" (200 to 300 US dollars per TEU). It is expected that the empty voyage rate will remain between 5% and 8% until the fourth quarter, as shipping companies prioritize high-yield routes, resulting in tight capacity supply.
Demand for Chinese exports to West Africa-including textiles, machinery, electronics, and construction materials-remains robust, driven by population growth and infrastructure investment. However, profit margins are under severe pressure: logistics costs now account for 35–40% of total export costs, up from 20–25% in 2024.
Although the sea freight charge and shipment schedules for various routes are currently increasing, Yashanway still maintains a fast delivery time. The delivery time for pipe manufacturing equipment is 2-3 months, while for supporting accessories and building materials, it only takes 15-30 days. Once the goods are ready, our company will find the most optimal shipping method for each customer to reduce shipping costs and waiting time.